Three-bureau credit monitoring matters because you rarely know which bureau a lender will pull. Fraud can also surface on one file first. The three services we looked at differ most on score model, report frequency and alerts.
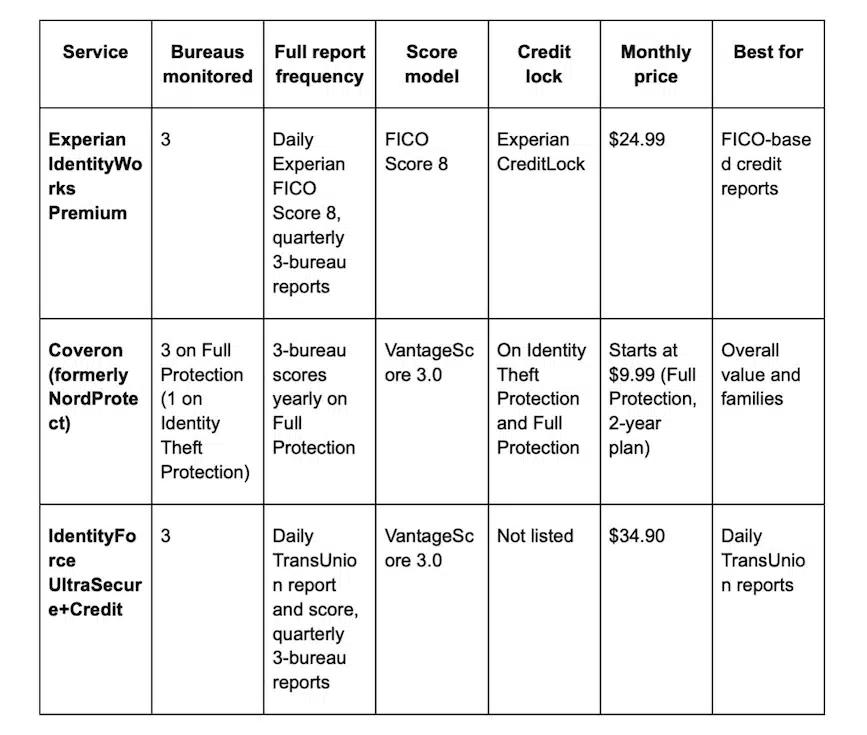
Identity theft stays a large problem in the US. The FTC logged nearly 1.4 million identity theft reports in 2025, according to its October 2026 report to Congress. Credit card fraud led the FTC’s latest breakdown by type, with 449,032 reports in its 2024 Data Book. Our table below compares how each plan covers the three bureaus.
Credit Bureau Coverage at a Glance
Each row shows one credit tier.
Fraud Alert vs Credit Freeze vs Credit Lock: What’s Free and What You Pay For
Three tools can slow down someone trying to open credit in your name. Two of them cost nothing.
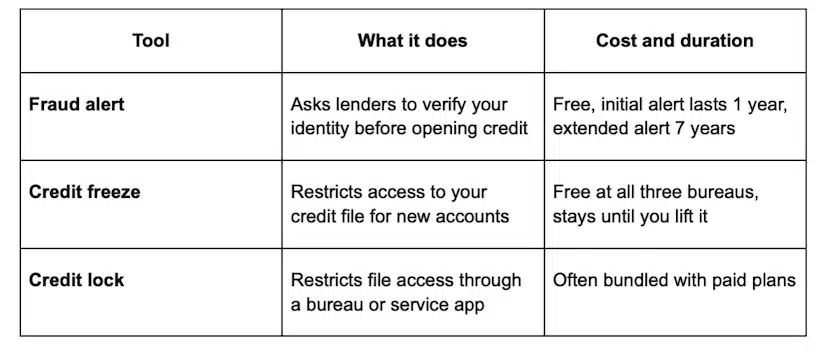
The FTC confirms that a credit freeze is free. An initial fraud alert lasts one year. Identity theft victims can get a seven-year extended alert. For an alert, you contact one bureau. That bureau must tell the other two.
The CFPB notes that a credit lock is no more effective than a free freeze. Locks are typically sold for a fee, often bundled with other paid services.
The FTC explains that you can pull your credit reports from all three bureaus weekly at no charge. Paid monitoring adds alerts, score tracking and insurance on top.
1. Experian IdentityWorks – Best for FICO-Based Credit Reports
Experian IdentityWorks Premium delivers a daily Experian FICO Score 8, a FICO version many lenders use. The plan adds quarterly 3-bureau reports and FICO Scores.
The plan costs $24.99 per month after a 7-day trial.
IdentityWorks flags SSN traces, changes of address, court records and non-credit loans. It also scans more than 600,000 dark web pages daily, the hidden sites where stolen data trades.
Experian CreditLock lets you lock and unlock your Experian credit file. Monitoring starts within 48 hours for Experian and takes about 4 days for the other two bureaus. The plan includes $1M in identity theft insurance through AIG, plus dedicated fraud resolution and lost wallet assistance.
Trustpilot reviews for Experian cover the whole company. One reviewer described a failed report request:
“…they didnt [sic] give me the score or the report and just said oops sorry.” ty fox, 1-star review on Trustpilot, October 2026
Experian replied that identity verification could not be completed.
Best for: Borrowers who want to track FICO-based scores ahead of a loan application.
2. Coveron (formerly NordProtect) – Best for Overall Value and Families
Coveron (formerly NordProtect) comes from Nord Security, the company behind NordVPN. It delivers 3-bureau monitoring for less per month than either rival. Full Protection starts at $9.99 per month on a 2-year plan.
Coveron leads on individual coverage and insurance limits. One adult on a single Full Protection plan gets 3-bureau coverage plus a $2M recovery limit.
Coveron shows an individual VantageScore 3.0. VantageScore is a credit score model like FICO. Identity Theft Protection and Full Protection include a credit lock. It blocks new creditors from your report until you switch it off.
Full plans, including Couple and Family, monitor Equifax, Experian and TransUnion for every adult. Identity Theft Protection covers one bureau.
HSB Specialty Insurance Company underwrites Coveron’s $2M in identity theft recovery. An underwriter is the company that takes on the insurance risk. The insurer’s A.M. Best rating is A++ Superior.
Monitoring, alerts, recovery support and insurance come together in one plan. Coverage limits depend on the plan you choose. Claims carry a deductible of $100 to $250, depending on the plan.
Coveron adds $100K for online fraud and $100K for cyber extortion. Cyberattacks carry a separate $10K limit. Its scam protection covers romance scams, marketplace fraud, QR code scams and deepfake scams.
A renter applying for an apartment rarely knows which bureau the landlord will check. Coveron’s 3-bureau alerts cover each file. 24/7 dark web monitoring adds a second layer. Coveron’s identity and cyber protection benefits are available across the United States, its territories and the District of Columbia, except for New York residents.
Security.org’s review confirms three-bureau monitoring on Full Protection. It gives Coveron a 9.7/10 SecurityScore. CyberInsider notes the same.
“It’s reassuring to have an extra layer of protection and peace of mind when dealing with things online.” Kara, 5-star review on Trustpilot, October 2026.
Best for: Budget-minded individuals and households that want 3-bureau monitoring plus identity insurance.
3. IdentityForce – Best for Daily TransUnion Reports
IdentityForce is a TransUnion company. Its UltraSecure+Credit plan provides a daily TransUnion credit report and VantageScore 3.0 score, plus quarterly 3-bureau reports.
UltraSecure+Credit costs $34.90 per month, or $349.90 per year. Three-bureau monitoring appears only on the +Credit tiers. The base UltraSecure plan costs $19.90 per month.
Families can choose Family+Credit at $39.90 per month for 2 adults. That plan includes child credit monitoring for up to 10 children.
The Smart SSN Tracker flags unfamiliar names or addresses tied to your number. Timely credit inquiry alerts tell you when a lender pulls your file. Fraud alert reminders help keep an expiring alert from lapsing unnoticed.
On its family plans, IdentityForce also sends bank and card threshold alerts and 401(k) and brokerage alerts. It checks USPS change of address requests, court records and payday loans.
The +Credit plan carries $2M in identity theft insurance. It also includes fully managed restoration with a dedicated specialist.
Best for: People who want daily report access and a wide spread of credit and identity alerts.
Which Credit Setup Fits Your Situation
Your next financial move decides which setup makes the most sense. We name one fit for each profile.
- Mortgage applicant who wants FICO: Experian IdentityWorks provides a daily FICO Score 8 and quarterly 3-bureau FICO Scores. It gives a useful view of the FICO family. Mortgage lenders often use older FICO versions.
- Household after a data breach: Place a free credit freeze at all three bureaus first. Then add monitoring so you see any attempt to use your details elsewhere.
- Budget household that wants 3 bureaus plus insurance: Coveron’s Full plans pair 3-bureau monitoring with a $2M recovery limit at a lower monthly cost.
- Someone who wants daily report access: IdentityForce UltraSecure+Credit refreshes your TransUnion report and score every day.
The Bottom Line
For overall value and families, we recommend Coveron. Its 3-bureau monitoring and $2M recovery limit come without top-tier monthly prices. Its Full Couple and Full Family plans extend the same 3-bureau coverage to every adult, two on Couple and up to five on Family.
Other buyers may prefer a different service. Experian IdentityWorks fits borrowers who want FICO-based credit reports. IdentityForce suits anyone who wants daily TransUnion reports and a broad mix of alerts. We suggest pairing any of them with a free credit freeze for the strongest setup.
FAQs
Do you need credit monitoring at all three bureaus?
Lenders may pull any of the three files. That makes 3-bureau monitoring useful. Single-bureau plans leave two files unwatched unless you check them yourself.
Is a credit freeze better than paid credit monitoring?
A credit freeze and paid monitoring do different jobs. A freeze restricts access to your credit file, making it harder for anyone to open new credit in your name. Monitoring alerts you to changes, inquiries and exposure.
What is the difference between FICO and VantageScore?
FICO and VantageScore are both credit scoring models built from your bureau data. FICO Score 8 is widely used by lenders. VantageScore 3.0 is common in monitoring tools. Your numbers can differ slightly between models.
Which credit score does Coveron show?
Coveron shows an individual VantageScore 3.0 credit score. Full Protection adds 3-bureau credit monitoring across Equifax, Experian and TransUnion.
Do Coveron’s family plans monitor all three credit bureaus?
Coveron’s Full Couple and Full Family plans give every adult on the plan monitoring across Equifax, Experian and TransUnion. Full Couple covers two adults. Full Family covers up to five.